

This article was created from a Forvm event, Life-Cycles, on 30th September, 2026
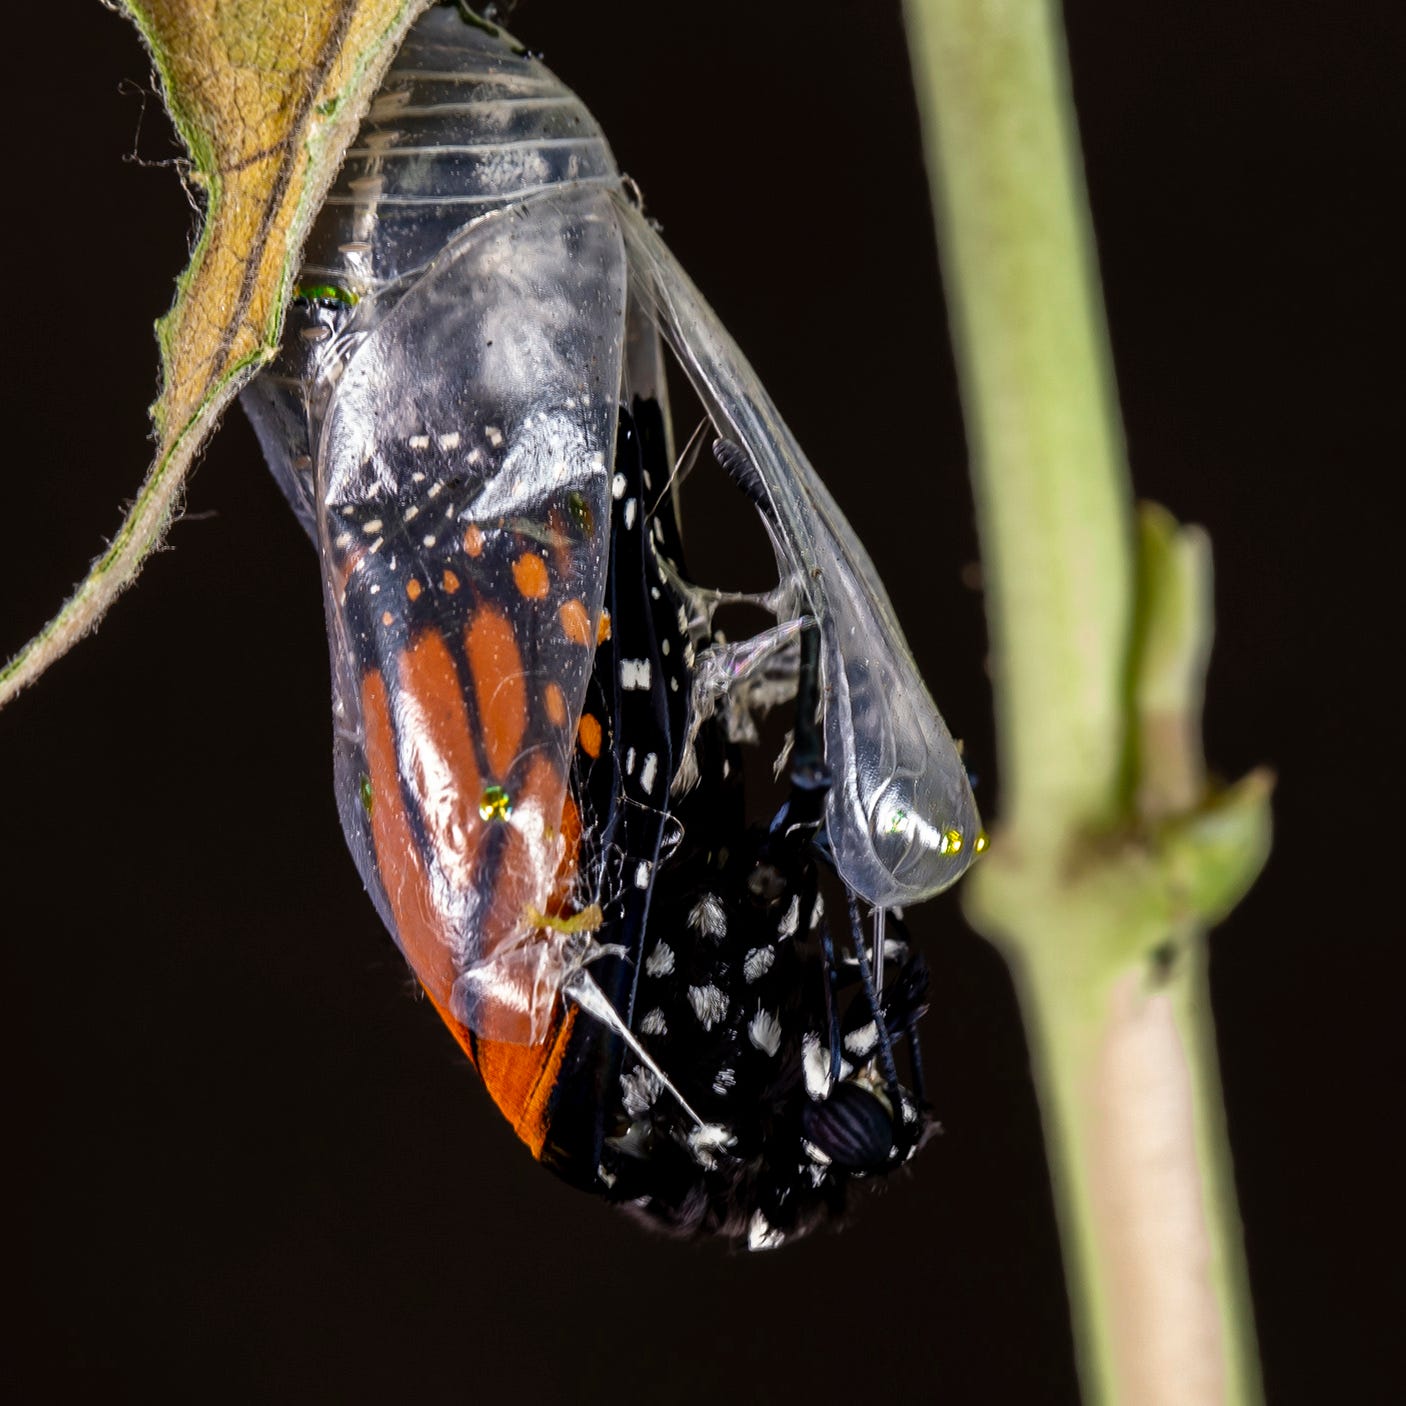
What counts as a life cycle
The term is applied loosely. Many consultancy diagrams show a process that loops back to the start once the work is done, which is a repeating process rather than a life cycle. A true life cycle has a distinct end, even if something else takes over afterwards: a product replaced, a company absorbed or closed. Whether the cycle is visible also depends on the viewpoint. From inside, a life looks like a straight line from birth to death; from far enough above, the parts are reused and the pattern repeats. A life cycle is also never isolated, because it sits within systems that interact with it.
Companies: act your age, or look ahead?
One view is that a company should act its age: once mature, it should return cash to shareholders and let its assets and people be used elsewhere. Philips is the usual example, and it can be read two ways. One reading is that it was a mistake. Its engineers developed lithography technology that the company judged to be outside its interests, and that technology became ASML, now worth far more than Philips itself. The other is that letting go was the right course: the assets went to work elsewhere, and shareholders were spared a management looking for new ventures to justify its own survival.
The record is more mixed than either reading. Philips did not simply drop these ventures. ASML began in 1984 as a joint venture with ASM International, and Philips was the largest founding investor in TSMC, supplying capital, technology licences and its first chief executive. Both were set up at arm’s length, with partners and a minority stake, which may be the way to encourage a new business without smothering it. Philips later sold both holdings. That bears on a common failing: large firms tend to be poor at nurturing small ones, because they run them by the rules suited to large, capital-heavy operations.
The same question applied to a chemical company that set out to break its boom-and-bust cycle, came close to bankruptcy through an execution error, and then recovered. The strategy may have been sound, but the recovery looked better for management than for shareholders, who could have moved their money elsewhere. Whether shareholder value should be the yardstick at all was also questioned. A more practical suggestion was that large organisations hold several life cycles at once and need different people for each. The people who run mature plants are not necessarily the ones who should start new ventures. Decisions to exit a market are better made case by case than by doctrine.
Products and technologies
Pharmaceutical products follow a fixed path from discovery through development and patent protection to generic competition, so the company must keep finding something new that others cannot copy. Technologies also shift underneath, from small molecules to proteins to genetic engineering, and firms like Nokia show the cost of missing the next one.
Decline is not always accepted. One agrochemical product is still sold fifty years after patenting, and an old beer brand regained value by being made scarce and more expensive. Others drop a product on a rational view of the market. Stage also changes the skills needed: launch and growth call for different people than maturity, where cost and defending against decline dominate. A parable about the wheel illustrates this. Once a technology simply works, buyers care about range and colour, which is why new phones seem to be announced mainly through new colours.
Imposed life cycles
Some cycles come from outside the market. Patent expiry is a deliberate regulatory cycle, intended to keep medicines affordable while rewarding innovation. The planned end of combustion-engine sales spurred investment in electric cars, and the phase-out of CFCs produced replacement chemicals and, apparently, a recovering ozone layer. Management fashion produces a third kind: periods favouring divestment, then vertical integration, with little rationale beyond the trend.
Misaligned cycles and inertia
For procurement, the problem is rarely one cycle but the mismatch between several. A mature buyer, a young supplier and an experimental technology may all sit under a contract of five to ten years. Procurement also sees technologies moving faster in the market than inside its own organisation, which makes its warnings unwelcome but valuable.
Finally, there was the suggestion that human laziness and attachment to comfort drive much of this. Organisations and sourcing relationships settle into habit. Deliberately ending something can shake that loose, though such experiments sometimes fail.
Participants in the SWISSUES Forvm event on which this article is based were Armin Scharlach, Pramod Prasanth, Stephen Fulton, Ercan Solmaz, Halyna Yokovleva and Bill Young. The article is edited with assistance from Anthropic’s Claude LLM.